projektae
Receiving a substantial amount of money unexpectedly can change a person’s financial circumstances almost overnight. An inheritance, proceeds from selling a business, an insurance settlement, or another significant payment may create opportunities that previously seemed out of reach.
However, a financial windfall can also introduce complicated decisions.
Should outstanding debts be repaid immediately? How much should remain accessible? Is it appropriate to invest the money, purchase property, or reconsider retirement plans?
Although receiving additional funds may provide greater financial flexibility, making rushed decisions can create unnecessary risks.
For Canadians experiencing a significant change in wealth, thoughtful financial planning begins with understanding the money’s source, reviewing existing responsibilities, and identifying long-term priorities.
Why Taking Time Before Making Major Decisions Matters
A financial windfall can bring excitement, relief, uncertainty, or conflicting emotions.
Someone receiving an inheritance may also be navigating the loss of a loved one, while a business owner receiving sale proceeds may be adjusting to a major professional transition.
These circumstances can make immediate financial decisions particularly challenging.
Rather than rushing into major purchases or investments, individuals may benefit from allowing time to understand their options.
For example, someone who receives a substantial inheritance might initially consider purchasing a larger home. However, reviewing retirement goals and ongoing household expenses could reveal other priorities.
Taking time does not mean avoiding financial decisions indefinitely.
It means separating immediate obligations from choices that require additional planning.
Understanding the Source of the Windfall
Not every financial windfall has the same characteristics.
The source of the funds can influence ownership arrangements, documentation requirements, taxation, and investment planning.
Inheritance and Estate Distributions
An inheritance may involve cash, investments, real estate, or other assets.
The financial implications can depend on the type of property received, the estate’s circumstances, and applicable tax rules.
Business-Sale Proceeds
Selling a business may produce substantial proceeds, but transaction expenses, ownership arrangements, and potential tax obligations require careful review.
Settlements and Other Payments
Insurance payments, legal settlements, and other financial awards may involve different considerations depending on their purpose and structure.
Before making commitments, recipients should confirm what they have received and whether any restrictions or outstanding obligations apply.
Reviewing Potential Tax Implications
One of the most important early steps is understanding whether the windfall creates tax obligations.
Canadian tax treatment depends on the nature of the payment and the recipient’s circumstances.
For example, receiving an inheritance is not necessarily treated the same way as realizing a gain from selling business shares.
Similarly, different components of a settlement may have different tax implications.
The Canada Revenue Agency provides guidance on reporting income and understanding tax obligations.
Rather than making assumptions, individuals should review relevant documents with a qualified tax professional.
Where appropriate, some funds may need to remain available until potential obligations are clarified.
Making major financial commitments before understanding these responsibilities could create avoidable liquidity problems.
Evaluating Outstanding Debt and Financial Obligations
A windfall provides an opportunity to review existing financial commitments.
These may include mortgages, personal loans, credit cards, business obligations, or other liabilities.
However, repaying every debt immediately is not automatically the best decision.
The appropriate approach depends on interest rates, repayment conditions, available cash, tax considerations, and broader financial goals.
Review Borrowing Costs
High-interest obligations may deserve attention because they can create ongoing financial pressure.
Other debts may have different repayment terms or penalties that should be considered.
Consider Future Cash Requirements
Using most of a windfall to eliminate debt may leave insufficient funds for emergencies, taxes, or planned expenses.
A complete review helps balance debt reduction with the need to maintain financial flexibility.
Establishing Emergency Reserves and Short-Term Liquidity
Before making long-term investments, individuals should consider how much money needs to remain readily accessible.
Unexpected household repairs, employment changes, healthcare expenses, and family responsibilities can create unplanned financial needs.
An emergency reserve provides resources for situations that require relatively quick access to money.
The appropriate amount varies according to household expenses, income stability, dependants, and other circumstances.
Someone who recently sold a business and no longer receives regular employment income may have different liquidity needs from a professional with a stable salary.
Money intended for near-term expenses should be considered separately from funds allocated to longer-term investment objectives.
Identifying Long-Term Financial Priorities
Once immediate obligations are understood, a windfall recipient can consider how the money may support future goals.
These goals might involve retirement, education, housing, family support, charitable giving, or maintaining financial independence.
A useful starting point is organizing objectives according to their expected time horizons.
For example, funds intended for a home purchase in the near future may require a different approach from assets intended to support retirement decades later.
Some individuals may also want to revisit existing financial plans.
A substantial windfall can change the resources available, but it does not eliminate the need for realistic assumptions about spending, future income, and financial risks.
Reviewing Investment Risk and Diversification
Investing a windfall requires more than selecting assets with attractive potential returns.
Investment decisions should reflect individual objectives, risk tolerance, time horizons, and liquidity needs.
Understanding Investment Concentration
A person receiving company shares or other investments may already have significant exposure to a particular business or sector.
Adding further investments without reviewing existing holdings could increase concentration risk.
Diversification can help manage exposure across different investments, although it cannot eliminate market risk.
Evaluating the Existing Portfolio
A professional portfolio review can help individuals examine existing assets, investment allocation, fees, and potential risks before making major changes.
The objective should be to understand how newly acquired wealth fits within the complete financial picture.
No investment strategy guarantees positive returns or protection from losses.
Reconsidering Retirement and Family Goals
Receiving a significant windfall may change retirement expectations.
Someone approaching retirement might consider whether additional assets affect their intended retirement date or income requirements.
A younger professional may prefer to continue working while using part of the funds to strengthen long-term savings.
Family priorities also deserve attention.
These may include supporting children, assisting aging relatives, or making future gifts.
However, financial generosity should be considered alongside the recipient’s own needs and obligations.
Before making substantial commitments, individuals can evaluate how those decisions may affect future flexibility.
Updating Estate and Succession Plans
A major change in wealth can also provide a reason to review existing estate planning arrangements.
Wills, beneficiary designations, powers of attorney, and ownership structures may need attention depending on individual circumstances.
For example, someone receiving significant assets may want to reconsider how their estate would be distributed.
A former business owner may also need to review arrangements that were established before selling the company.
Estate planning involves legal and financial considerations that vary by province, asset type, and family circumstances.
Qualified legal professionals can help explain the available options and relevant responsibilities.
Coordinating With Qualified Financial Professionals
A windfall can affect several financial areas simultaneously.
Investment decisions may interact with tax planning, debt management, retirement expectations, and estate arrangements.
For this reason, coordination between qualified professionals can be valuable.
An accountant may assess tax considerations, a lawyer may review legal or estate matters, and an investment professional may evaluate portfolio-related decisions.
Organizations offering comprehensive financial services can help individuals consider how different financial priorities fit within a broader plan.
When selecting advisers, recipients should review professional qualifications, relevant experience, fees, and potential conflicts of interest.
A Practical Checklist Before Using a Windfall
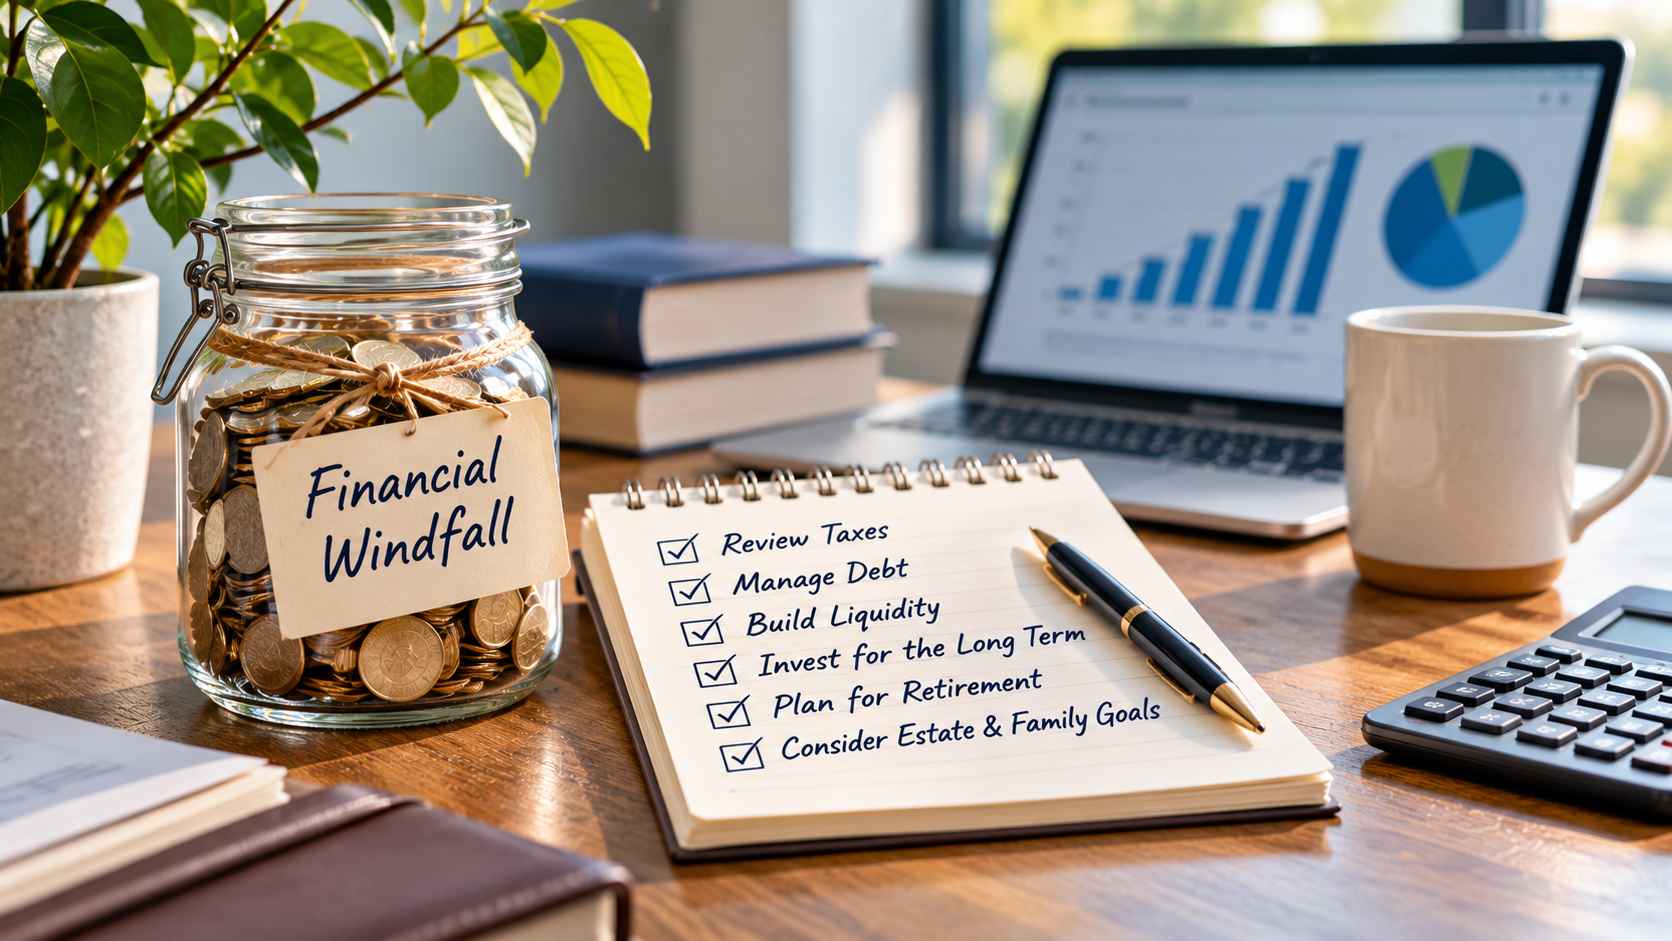
Before making significant financial commitments, consider the following steps:
- Confirm the source and ownership of the funds: Organize relevant documents and understand any conditions.
- Clarify tax obligations: Consult a qualified professional before assuming all funds are available to spend.
- Review current debts: Evaluate repayment terms alongside cash requirements.
- Establish liquidity needs: Identify immediate expenses and suitable emergency reserves.
- Define long-term goals: Consider retirement, family responsibilities, and other priorities.
- Review existing investments: Understand concentration, risk exposure, and diversification.
- Update important plans: Revisit estate documents and relevant financial arrangements.
These steps provide a starting point rather than a universal financial strategy.
Turning a Windfall Into a Thoughtful Financial Plan
Receiving a significant amount of money can create new opportunities, but the choices that follow deserve careful attention.
A windfall may affect taxes, investments, debt, retirement, family responsibilities, and estate planning in different ways.
Rather than immediately committing funds to major purchases or investments, recipients can begin by understanding their financial position and identifying realistic priorities.
Professional guidance may help coordinate these decisions, particularly when the money comes from complex transactions or involves substantial assets.
Ultimately, managing a windfall is not about making the fastest decision or pursuing the highest possible return. It is about developing a financial plan that reflects personal circumstances, protects appropriate flexibility, and supports meaningful long-term goals.